
Analysis
02 - 10 - 2026
IT Preview: Tech firms brace for muted Q2 as weak demand, longer decision-making cycles persist
Brokerages project tier-I constant currency growth to remain flat or negative as prolonged decision-making cycles continue to delay revenue conversion.
Indian Information Technology (IT) firms are likely to report a muted second quarter (Q2) as macroeconomic headwinds, Artificial Intelligence-driven disruptions, and delayed client spending continue to dampen performance. Traditionally, the Q2 is a seasonally strong period, but this time deal wins remain soft, client decision-making stays cautious, and discretionary spending stays curtailed amid macro uncertainty.
Tepid macro environment: Motilal Oswal
The second quarter earnings for IT firms are likely to mirror the tepid macro environment, with quarter-on-quarter (QoQ) constant currency growth expected in the range of -0.5-3 per cent for large-caps, Motilal Oswal Financial Services (MOFSL) said in a report.
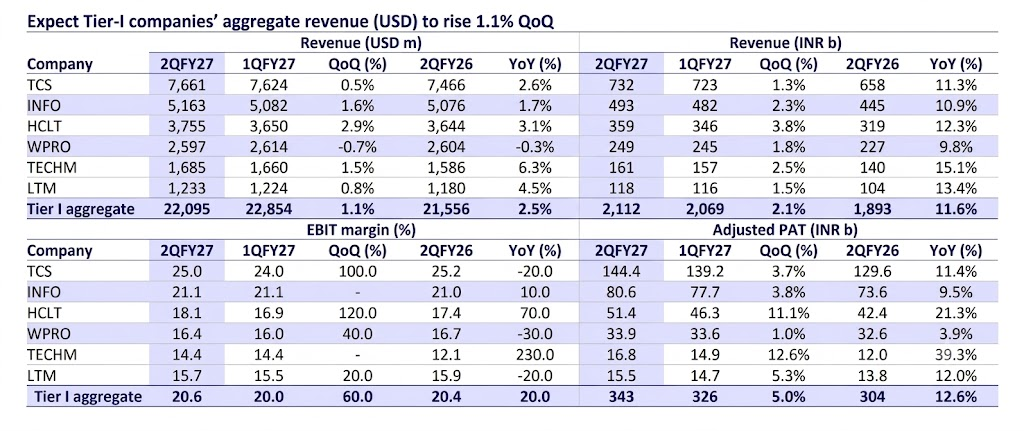
Mid-caps are expected to outperform once again, with growth ranging from 0-12 per cent, led by continued large-deal ramp-ups and inorganic contribution in some cases.
“We expect modest cross-currency headwind of 10-30 basis points for most companies,” MOFSL said.
“We expect demand commentary to remain soft into second quarter, despite it being a seasonally strong quarter, as macro pressures, interest rate hikes, artificial intelligence-related disruptions, and geopolitical overhang continue to weigh on discretionary spending and decision-making cycles. Against this backdrop, we do not expect QoQ growth acceleration across our coverage universe in Q2, with softness likely to extend into Q3 due to furloughs as well,” it added.
Most IT services providers are expected to remain range-bound. Sequential margin expansion is likely for Tata Consultancy Services (TCS), HCL Technologies (HCLT), Wipro, and LTIMindtree, driven by cost-efficiency measures, the reversal of wage-hike headwinds. Conversely, Infosys and Tech Mahindra are expected to stay broadly flat.
Seasonality fails to lift the print: HSIE Research
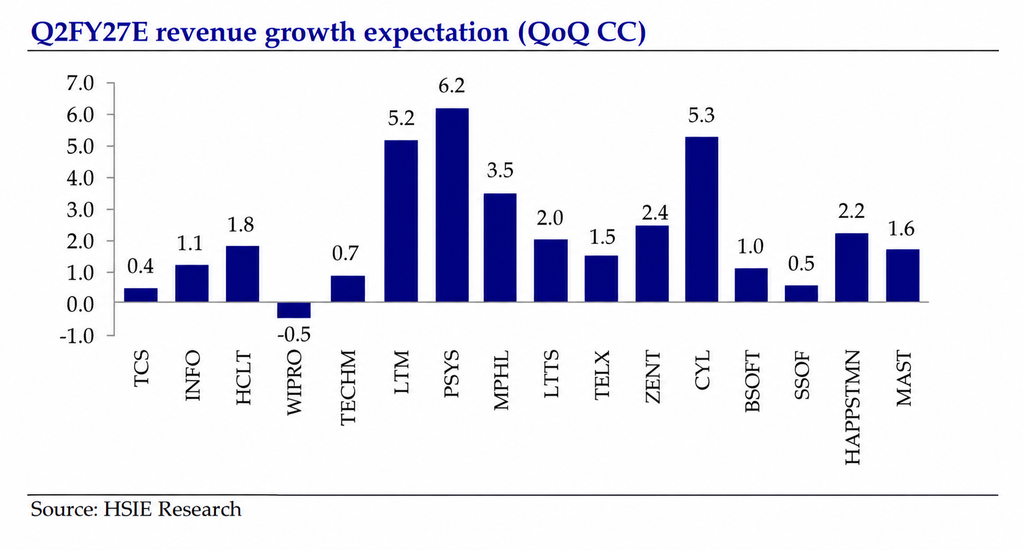
The Indian IT sector is set for another muted print in what is typically a seasonally strong quarter, with the Q2 constant currency growth projected at -0.4-2 per cent QoQ for tier-I companies and 0.6-6.3 per cent for mid-tier firms, partly aided by acquisitions, HDFC Securities (HSIE Research) said in a report.
Deal wins remain soft, client decision-making stays cautious, and discretionary spending stays curtailed amid macro uncertainty, while pricing pressure persists as AI-led productivity pass-through gets embedded into renewals and new deals, it said.
“Rupee depreciation, operational efficiencies, and elevated utilisation will offset the wage hikes impact, but AI-led deflation concerns continue to weigh on sector multiples. Indian IT companies maintain that direct Gen-AI deployment by enterprises remains difficult in complex, regulatory-heavy brownfield environments, keeping the role of SI vendors critical; the expected 6-7 per cent deflation impact is being offset by net-new AI-centric deal wins, though conversion remains slow,” it added.
Modest Q2: Anand Rathi
The IT sector will likely show a modest seasonal QoQ uptick in the second quarter rather than a demand revival, according to a report by Anand Rathi.
The report noted that Accenture’s latest results support this view, as overall demand, including discretionary spending, did not meaningfully change in the quarter. With deal flow dominated by cost take-out programmes, execution—specifically winning deals and ramping them up quickly—will be the differentiator.
The top six large-cap companies are estimated to grow at a median of about 1.1 per cent QoQ in constant currency (cc), compared with about 0.35 per cent in the first quarter of FY27. Both Q1 and Q2 are estimated to record 2.9 per cent YoY growth on a cc basis.
TCS expects a front-loaded quarter based on July and August metrics, but September is expected to be affected by rate hikes and Middle East weakness, particularly in the manufacturing and retail sectors.
Infosys and HCL Tech will benefit from about 50 BPS and about 110 BPS of inorganic contribution, respectively. Infosys is expected to report under 1 per cent organic growth. Assuming a flat third quarter and a subdued fourth quarter, it expects Infosys to end FY27 at about 1.7-2 per cent growth, of which about 1.5 per cent is organic, excluding Versent.
HCLT is expected to post 2.5 per cent QoQ growth, including the inorganic contribution from the Hewlett Packard Enterprise telco business and Jaspersoft.
Weakness is expected in Wipro, with an about 2 per cent organic decline, or an about 1.5-1.8 per cent sequential organic decline. Guided overall sequential growth is between -1.5 per cent and 0.5 per cent. Given the Alpha Net acquisition delay, Wipro’s overall QoQ CC growth is estimated at about -1 per cent.
Tech) is expected to grow about 1-1.5 per cent, as the Orange deal ramp-up offsets a Q1 base that included a one-off manufacturing benefit.
LTIMindtree is expected to post sub-1 per cent QoQ CC growth in Q2, with FY27 estimated organic growth of 5-5.5 per cent. The report expects a delayed Central Board of Direct Taxes (CBDT) ramp-up exacerbated by Middle East consumer packaged goods weakness to impact LTM. TechM and LTM are Anand Rathi’s top large-cap picks.
Earnings before interest and taxes (EBIT) margins for the top six IT firms are expected to be broadly flat. About 1 per cent INR depreciation offers limited cushion against wage hikes, acquisition amortisation, and AI investments. Hedge losses for TechM and LTM are a swing factor for profitability. TechM is expected to hold margins despite a 70-75bps wage-hike impact.
Weaker H1
A weak Q1, followed by a subdued Q2, would translate into a weaker H1 (first half of the fiscal). With H1 tracking below the run-rate required to sustain the upper end of FY27 guidance, the ask from H2 to bridge the gap becomes increasingly impractical, MOFSL said.
“If Q2 revenue performance is weaker than our estimates, we could see some guidance cuts. We expect HCLT to maintain its FY27 guidance due to better deal visibility,” MOFSL added.
“With H1 tracking below expectations, FY27 recovery rests on H2, which includes the seasonally soft furlough-impacted Q3, tempering full-year expectations. Growth recovery is a function of execution, as new deals are increasingly outcome-driven, pricing is agent-augmented, and renewals come at a discount,” HSIE Research said.
“We anticipate Infosys will cut its FY27 YoY CC growth guidance by 50 BPS to 2-3 per cent (from 2-3.5 per cent) and HCL Tech will trim the upper end of its services guidance to 1.5-3 per cent (from 1.5-3.5 per cent). Wipro is likely to guide -1-0 per cent QoQ CC for Q3, factoring furloughs, and L&T Tech will aim for mid-single digit growth for FY27,” HSIE Research added.
Margin guidance is expected to remain stable, supported by currency tailwind, staggered wage hikes, and higher utilisation. Infosys is likely to maintain a margin band of 20-22 per cent, HCL Tech 17.5-18.5 per cent, and TCS 26-28 per cent.
Anand Rathi expects IT firms to post a subdued growth in FY27. FY27 is shaping up as the industry’s fourth consecutive year of subdued growth, with competitive intensity rising. The headwinds are incremental budgets flowing to AI infrastructure and AI-native players, AI-led deflation in legacy work, GCC insourcing, and a macro backdrop of rising crude and likelihood of Fed rate hikes.
With H2 seasonally softer, commentary on furloughs, discretionary spend and the durability of current demand will set the tone for FY27 estimates.
A real yet nascent counter-case is that AI is creating new growth opportunities rather than posing a pure deflationary threat: companies are describing demand as unchanged but pointed to modernisation, GenAI implementation, agentic workflows and transformation programmes, as a larger medium-term opportunity with discretionary spend is expected as clients move from AI experimentation and infrastructure build-out to scaled deployment.
“We continue to remain structurally positive on IT and expect enterprise software to monetise through FY27,” Anand Rathi added.
If you spotted a mistake or have feedback on this story, write to us at editor@newsassociate.com. Email us your press releases on the same ID.
Most Popular
4 days ago
CG Power’s consolidated Q2 net profit rises 44% to ₹409 crore
A sharp rise in Power Systems margins, swelling order book underpin the engineering conglomerate's…
3 days ago
Tech Mahindra partners with SpaceXSI to bring Grok AI coding tools into enterprise workflows
The collaboration will target legacy application modernisation, software development and developer productivity, with a…
3 days ago
Kotak Mahindra Bank’s profits soar, but margins refuse to join the party
Management expects the full-quarter impact of FCNR(B) deposits to weigh on margins in the…
1 day ago
India’s Mumbai records 3,145 luxury property transactions in H1 FY27
The city registered 3,145 luxury residential property transactions worth ₹32,623 crore between April and…
