
Analysis
12 - 10 - 2026
Preview: Telecom firms set for a moderate Q2
The consistent technological migration from legacy 2G networks to advanced 4G and 5G platforms remains the primary engine driving topline growth
Indian telecom companies are set for a moderate performance in the second quarter (Q2), banking on technological upgrades from legacy networks, favourable pricing and ongoing customer additions.
The operating environment remains fundamentally sound despite the absence of immediate headline tariff revisions during the period, according to earnings previews by brokerages such as Centrum Broking, J.P. Morgan, Nomura, and Emkay Global.
The brokerage firms said that consistent technological migration from legacy 2G networks to advanced 4G and 5G platforms remains the primary engine driving topline growth and sequential Average Revenue Per User (ARPU) enhancement across the major telecom service providers.
Operators continue to harvest the benefits of technology for upgrades and widening networks, as strategic plan adjustments and ongoing fundraising discussions set the tone for near-term sector momentum. The operating environment is characterised by a more disciplined three-plus-one player structure, which continues to foster a favourable pricing climate despite the absence of immediate headline tariff revisions during the quarter.
The consistent technological migration from legacy 2G networks to advanced 4G and 5G platforms remains the primary engine driving top-line growth and sequential ARPU enhancement across the major telecom service providers, reports by Nomura and Emkay Global said.
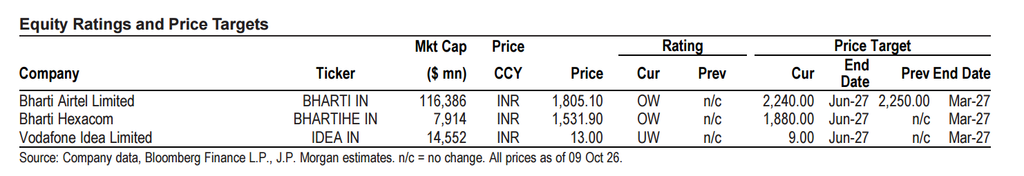
Bharti Airtel, Bharti Hexacom
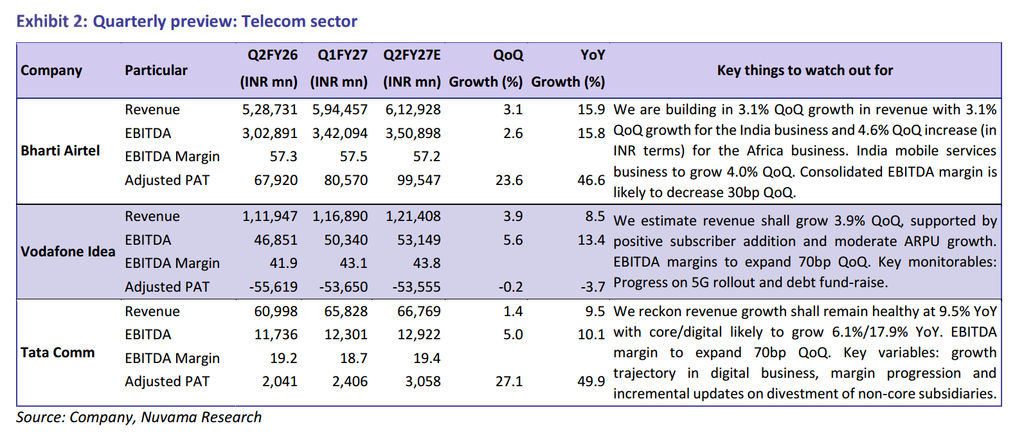
Bharti Airtel is expected to post a consolidated revenue increase of roughly 3.1 per cent on a quarter-on-quarter basis, reaching ₹603,369 million, according to a report by Centrum Broking. This would be driven driven by robust performance across both domestic wireless operations and the African subsidiary.
Nomura’s estimates India wireless revenue at ₹310.2 billion, underpinned by organic subscriber additions of 1.9 million and an ARPU tick-up to ₹272 per month. Emkay Global points out that Bharti Airtel tactically withdrew specific lower-value prepaid plans offering limited daily data allowances during the quarter to actively encourage subscriber premiumisation toward higher-value packages.
J.P. Morgan notes that operational catalysts for the parent entity include aggressive debt deleveraging, rising dividend payouts, and strong execution in enterprise and home broadband adjacencies. J.P. Morgan and Nomura maintain Overweight and Buy ratings on Bharti Hexacom, projecting strong revenue and EBITDA expansion. They emphasise that Hexacom’s lower structural leverage, superior return on capital employed, and lower initial teledensity in its operating circles justify its valuation premium over broader industry peers.
Reliance Jio
Reliance Jio is expected to maintain its dominant market position by adding about 8 million subscribers during the quarter, pushing its total end-of-period subscriber base to 541.3 million, Centrum Broking and Nomura said.
J.P. Morgan and Centrum attribute the anticipated revenue growth of 2.6 per cent quarter-on-quarter to steady fixed wireless access additions, sustained 5G network expansion across more than 95 per cent of districts nationwide, and a higher number of operational days in the quarter.
Nomura estimates that Jio Platforms will achieve an EBITDA of ₹220.5 billion, marking a 17 per cent increase year-on-year, while maintaining a stable EBITDA margin of about 54.6 per cent. Analysts observe that Jio’s aggressive push into fixed-broadband services and digital enterprise solutions continues to insulate its financial print against broader macroeconomic softening.
Vodafone Idea
Vodafone Idea is expected to post modest sequential revenue growth of about 1.1 per cent, alongside positive subscriber net additions of roughly 1 million, signalling a welcome stabilisation after several quarters of persistent customer losses, Centrum Broking, J.P. Morgan and Nomura said.
Nomura estimates that the operator’s blended ARPU will edge higher to about ₹181 per month. Emkay Global and J.P. Morgan said that the management commentary regarding active negotiations with a banking consortium led by the State Bank of India to secure a $3.5 billion or ₹250 billion debt fundraising program remains critical. This capital injection is considered vital for funding Vodafone Idea’s broader INR 450 billion capital expenditure program spanning financial years 2027 through 2029, which aims to accelerate its 4G coverage footprint and strategic 5G rollouts.
Indus Towers
In the passive infrastructure space, Indus Towers is expected to report a 1.7 per cent sequential revenue increase, supported by a 1.5 per cent growth in co-locations as Vodafone Idea actively ramps up site expansion and network capacity, Centrum Broking and J.P. Morgan said.
Nomura adds that Indus Towers is expected to add around 4,000 towers and 6,000 tenancies during the quarter, helping maintain a stable tenancy ratio of 1.62 times. Furthermore, diversified digital and internet entities under coverage, such as Info Edge, Nazara Technologies, and eMudhra, are projected by Centrum and Nuvama Institutional Equities to deliver steady revenue expansion across their respective recruitment, gaming, and enterprise trust solution segments.
While elevated marketing expenses and customer acquisition costs are anticipated to exert temporary pressure on near-term EBITDA margins, the broader fundamental growth trajectory across the digital economy remains intact.
If you spotted a mistake or have feedback on this story, write to us at editor@newsassociate.com. Email us your press releases on the same ID.
Most Popular
4 days ago
CG Power’s consolidated Q2 net profit rises 44% to ₹409 crore
A sharp rise in Power Systems margins, swelling order book underpin the engineering conglomerate's…
1 day ago
India’s Mumbai records 3,145 luxury property transactions in H1 FY27
The city registered 3,145 luxury residential property transactions worth ₹32,623 crore between April and…
3 days ago
Kotak Mahindra Bank’s profits soar, but margins refuse to join the party
Management expects the full-quarter impact of FCNR(B) deposits to weigh on margins in the…
4 days ago
DCGI Approves Toripalimab Combination Therapy for Advanced Oesophageal Cancer in India
Dr Reddy’s Laboratories’ Zytorvi, combined with cisplatin and paclitaxel, gains a first-line indication for…
