
Analysis
24 - 09 - 2026
Pharma to see stronger dose of revenue growth at 11-13% this fiscal
However, inflation will squeeze operating margins, preventing this growth from boosting earnings: Crisil
India’s pharmaceutical sector is poised for stronger growth this fiscal, with revenue set to rise 11-13 per cent compared with 8 per cent last fiscal, driven by accelerating exports and firmer domestic demand.
Yet, this growth spurt is unlikely to flow through fully to earnings, as inflation in raw material, energy and freight costs is expected to compress operating margins by 150-200 basis points (BPS). Nevertheless, strong cash generation, liquidity and healthy balance sheets should keep the sector’s credit profiles resilient, according to a report by Crisil Ratings, which analysed data of 190 pharmaceutical firms.
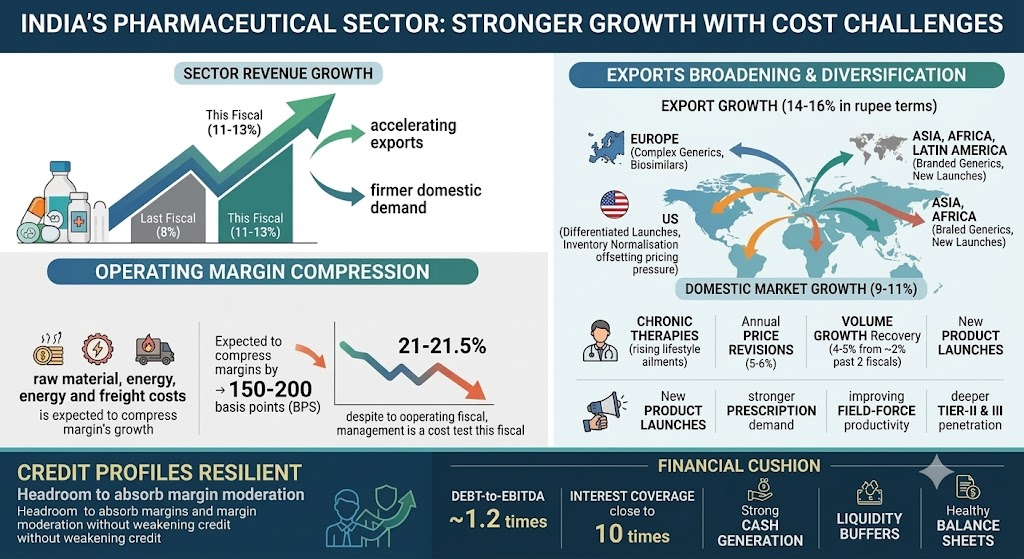
Dominated by generics, the sector derives almost equal revenue from domestic and export markets. Formulations account for about 83 per cent of exports, and of these, around 57 per cent are shipped to regulated markets and the remainder to semi-regulated markets. This diversified geographic footprint is becoming a key growth lever.
“Export growth is broadening beyond the US. Complex generics and biosimilars are expected to deepen the sector’s presence in Europe, while branded generics and new launches will accelerate growth across Asia, Africa and Latin America. In the US, differentiated product launches and inventory normalisation should partly offset continuing pricing pressure. This broader market and product mix will be the principal driver of export growth, which is projected at 14-16 per cent in rupee terms this fiscal,” Sehul Bhatt, Director, Crisil Intelligence, said.
Alongside the export upswing, the domestic market is expected to provide a solid second engine of growth, expanding 9-11 per cent this fiscal. Chronic therapies will remain the key growth driver, supported by the rising prevalence of lifestyle-related ailments. The market will also benefit from annual price revisions of 5-6 per cent and a recovery in volume growth to 4-5 per cent, compared with around 2 per cent in each of the past two fiscals.
The improvement in volumes will be driven by new product launches, stronger prescription demand, improving field-force productivity and deeper penetration into Tier-II and III markets.
“The sector’s growth momentum is strengthening, but earnings will face a cost test this fiscal, with operating margins expected to moderate by 150-200 basis points to 21-21.5 per cent. Higher energy, freight and feedstock costs amid geopolitical volatility in West Asia will outweigh near-term gains from rising operating leverage and a richer product mix. Nevertheless, robust balance sheets and sizeable liquidity buffers give companies the headroom to absorb this margin moderation without weakening credit profiles,” Aditya Jhaver, Director, Crisil Ratings, said.
That financial cushion is reflected in healthy credit metrics. Debt-to-EBITDA for Crisil-rated companies is expected to remain around 1.2 times, while interest coverage should stay close to 10 times this fiscal despite margin moderation, the report added.
If you spotted a mistake or have feedback on this story, write to us at editor@newsassociate.com. Email us your press releases on the same ID.
Most Popular
4 days ago
DCGI Approves Toripalimab Combination Therapy for Advanced Oesophageal Cancer in India
Dr Reddy’s Laboratories’ Zytorvi, combined with cisplatin and paclitaxel, gains a first-line indication for…
4 days ago
CG Power’s consolidated Q2 net profit rises 44% to ₹409 crore
A sharp rise in Power Systems margins, swelling order book underpin the engineering conglomerate's…
3 days ago
Kotak Mahindra Bank’s profits soar, but margins refuse to join the party
Management expects the full-quarter impact of FCNR(B) deposits to weigh on margins in the…
1 day ago
India’s Mumbai records 3,145 luxury property transactions in H1 FY27
The city registered 3,145 luxury residential property transactions worth ₹32,623 crore between April and…
