
News
4 days ago
CG Power’s consolidated Q2 net profit rises 44% to ₹409 crore
A sharp rise in Power Systems margins, swelling order book underpin the engineering conglomerate’s earnings, while semiconductor investments weigh slightly on profitability
CG Power and Industrial Solutions Limited posted a net profit of ₹409 crore on a consolidated basis for the second quarter ended September 30, 2026, led by a strong performance in its power systems business.
During the quarter under review, the company’s net profit rose 44 per cent from ₹284 crore recorded during the year-ago period, the company said in a press release.
“These results are a cumulative outcome of our teams executing with discipline, day after day, across every business by leveraging CG EDGE – our operating model. That consistency is the foundation we are building our company on, and it gives us confidence in sustaining this performance as we scale,” CG Group Chief Executive Officer (CEO) and Managing Director Amar Kaul said.
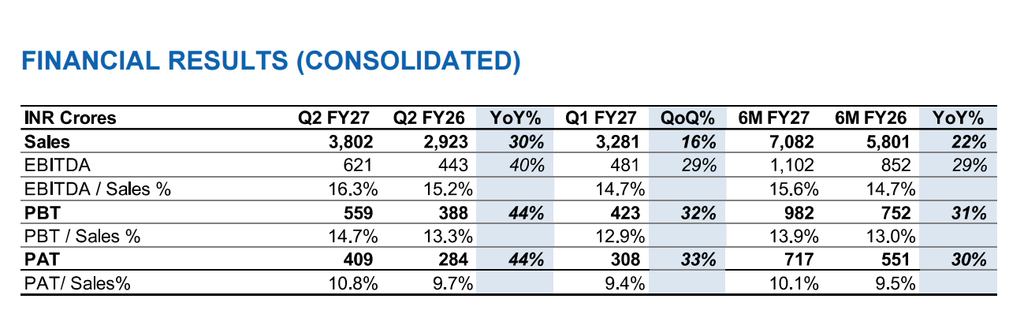
Its consolidated sales rose 30 per cent to ₹3,802 crore in Q2, compared with ₹2,923 crore in the corresponding quarter of FY26. Earnings before interest, taxes, depreciation and amortisation (EBITDA) rose 40 per cent to ₹621 crore (₹443 crore) on a year-on-year basis and was 29 per cent higher on a quarter-on=quarter basis from ₹481 crore.
The EBITDA margin improved to 16.3 per cent of sales from 15.2 per cent a year earlier and 14.7 per cent in the preceding quarter.
Its net profit margin at 10.8 per cent compared with 9.7 per cent a year earlier and 9.4 per cent in the previous quarter.
The consolidated results include the performance of operating subsidiaries in Sweden, Germany and the Netherlands (Drives and Automation Europe), CG DE Sub LLC, CG Adhesive Products Ltd (India), CG Semi Private Limited (India), G.G. Tronics India Private Limited, the Axiro Semiconductor Group, and other non-operating subsidiaries.
CG Power said the margin expansion was led by strong Power Systems performance, partially offset by continued talent investments across CG Semi and Axiro. The total impact on the semiconductor segment was ₹35 crore, or 91 basis points (bps).
Return on capital employed (ROCE), annualised, for the quarter was 25 per cent, including proceeds from the qualified institutional placement (QIP).
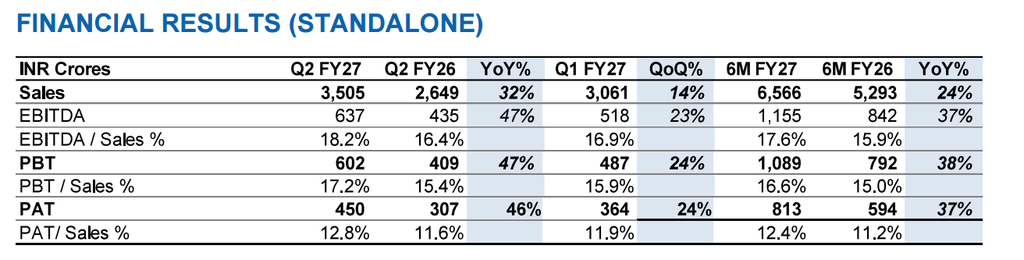
CG Power’s net profit on a standalone basis rose 46 per cent to ₹450 crore (₹307 crore) on a YoY basis, and a 24 per cent on a QoQ basis.
Order intake for the quarter was 78 per cent higher YoY at ₹8,485 crore, while the unexecuted order backlog as of September 30, 2026, was 58 per cent higher YoY at ₹23,646 crore.
For the first half (H1) of FY27, consolidated net profit rose 30 per cent to ₹717 crore (₹551 crore), while the net profit margin improved to 10.1 per cent from 9.5 per cent. The firm’s consolidated sales rose 22 per cent YoY to ₹7,082 crore from ₹5,801 crore.
In the Power Systems segment, sales rose 41 per cent YoY to ₹1,769 crore from ₹1,254 crore, while EBITDA climbed 70 per cent to ₹458 crore from ₹269 crore.
The board has approved a further investment of about ₹15.31 crore at the S3 Unit-II facility to enhance EHV circuit breaker capacity by 3,600 units a year, taking total capacity to 10,800 units a year. The addition is planned to be completed within six to nine months.
For the Gas Insulated Switchgear (GIS) brownfield project at Vilholi, Nashik, the board approved raising the capital expenditure to ₹44.62 crore from ₹35.17 crore, an additional ₹9.45 crore.
MOSFL: To benefit from capacity expansion
“CG Power’s Q2 earnings were ahead of our estimates. This outperformance versus our estimates was led by strong order inflow and revenue growth in power systems segment and better margins in industrial segment despite weak performance in railways within the industrial segment,” a report by Motilal Oswal Financial Services (MOFSL) said.
“Going forward, we expect CG Power to benefit from the recent capacity expansion at power systems for transformers, switchgear and circuit breakers, price hikes and a gradual demand recovery in the industrial segment, and a reduction of losses at CG-SEMI by FY28,” it said.
The brokerage firm has raised its estimates by 5 per cent for FY27, 9 per cent for FY28 and 10 per cent for FY29, baking in higher estimates for power systems. However, it has moderated margin assumptions for industrial systems.
MOFSL expects overall order inflows to register an 18 per cent CAGR over FY26-29.
If you spotted a mistake or have feedback on this story, write to us at editor@newsassociate.com. Email us your press releases on the same ID.
Most Popular
3 days ago
Tech Mahindra partners with SpaceXSI to bring Grok AI coding tools into enterprise workflows
The collaboration will target legacy application modernisation, software development and developer productivity, with a…
1 day ago
India’s Mumbai records 3,145 luxury property transactions in H1 FY27
The city registered 3,145 luxury residential property transactions worth ₹32,623 crore between April and…
4 days ago
DCGI Approves Toripalimab Combination Therapy for Advanced Oesophageal Cancer in India
Dr Reddy’s Laboratories’ Zytorvi, combined with cisplatin and paclitaxel, gains a first-line indication for…
4 days ago
CG Power’s consolidated Q2 net profit rises 44% to ₹409 crore
A sharp rise in Power Systems margins, swelling order book underpin the engineering conglomerate's…
